
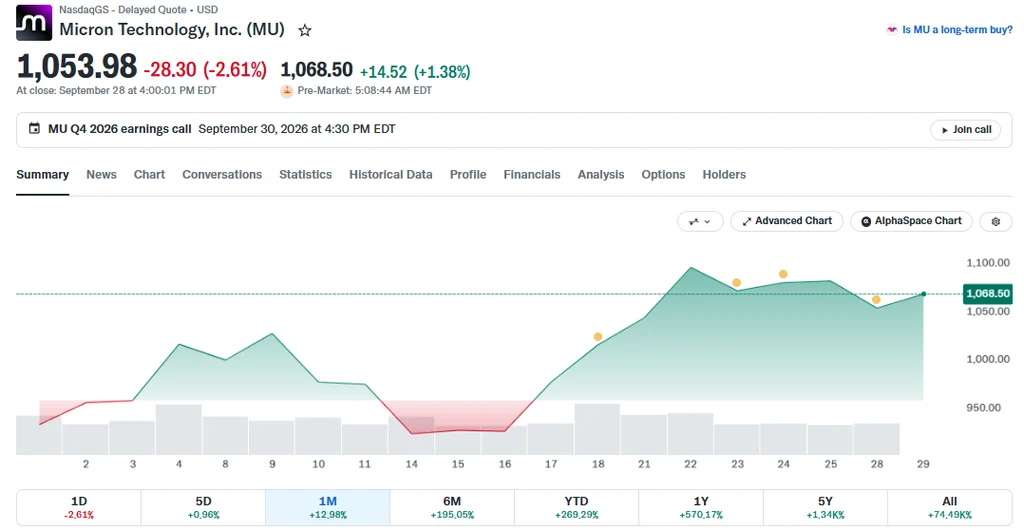
Wall Street has established a Micron stock price target between $1,500 and $1,600 leading up to the fiscal Q4 earnings report on September 30, keeping the overall Micron stock outlook firmly bullish. MU finished Monday at $1,053.98 and changed hands at $1,069.27 during pre-market trading. An average MU stock price target of $1,515 suggests an upside of roughly 44%. Following a 2026 rally of approximately 269%, investors are wondering if MU stock can climb higher. Analysts believe continued gains are possible provided that artificial intelligence demand remains strong and DRAM supply stays constrained.
Also Read: Micron Earnings: Can MU Stock Beat High Expectations?
Micron Stock in 2026: Price Targets, AI Demand And MU’s Next Move
Ultimately, the trajectory of Micron shares hinges on whether artificial intelligence memory demand sustains elevated earnings for a longer duration than observed in prior cycles. Although the stock retreated 2.61% on Monday after OpenAI temporarily halted training on certain AI models, StockAnalysis data shows that 36 out of 49 analysts still maintain a Strong Buy rating on Micron.
Baird, Rosenblatt And TD Cowen Stay Bullish
On Monday, Baird analyst Tristan Gerra bumped his price target from $1,280 to $1,520 while reiterating an Outperform rating. This updated target aligns closely with the consensus and implies about 44% upside relative to Monday’s closing price.
Gerra wrote:
“We are incrementally positive on Micron near- and medium term, owing to 1) the recent surge in agentic AI demand, notably driving CPU demand and which we expect will be ongoing next year; 2) a deceleration in [dynamic random access memory] supply bit growth outlook industrywide for 2027 versus this year; 3) a higher margin profile expected for [high bandwidth memory] next year.”
Meanwhile, Kevin Cassidy of Rosenblatt reaffirmed his Buy rating alongside a $1,500 target, anticipating another “beat-and-raise” performance on Wednesday. Krish Sankar of TD Cowen also maintains a Buy rating with a target of $1,600. Both analyst perspectives reinforce confidence in the broader Micron stock outlook.
Micron’s Own Guidance Backs The Bulls
Company leadership has likewise delivered robust projections that support the bullish sentiment. Micron’s fiscal Q4 guidance points to revenue of $50 billion (plus or minus $1 billion), a gross margin near 86%, and earnings per share of $31 (plus or minus $1). Whether MU stock rises post-earnings will depend on the company’s ability to exceed these figures.
Sanjay Mehrotra, Micron’s Chairman, President and CEO, stated:
“Micron’s record fiscal Q3 financial results and even stronger outlook for Q4 reflect the strategic value of memory in the AI era. Micron is investing at record levels in technology, products and supply to address our customers’ rapidly growing demand. We believe our multi-year Strategic Customer Agreements will significantly enhance the durability and predictability of Micron’s strong financial performance.”
A Rerating Could Lift The Micron Stock Outlook
As reported by MarketWatch, Sankar identifies potential for a valuation “rerating” for Micron. At the time of his assessment, the equity traded at roughly 5.8 times forward earnings, and he contends the multiple could reasonably approach nine times. Achieving this valuation does not require accelerated growth, merely prolonged earnings durability, which serves as the rationale behind his $1,600 price target. Expansion in the valuation multiple alone could further strengthen the Micron stock outlook.
At the same time, risks to these 2026 forecasts persist, including the possibility of accelerated supply additions, softer high bandwidth memory demand, and declining memory pricing.
Ultimately, the majority of analysts expect MU stock to climb, with the near-term outlook contingent on whether the September 30 report confirms that robust pricing power and margins are sustainable. Should that occur, the $1,500 to $1,600 target range remains an attainable projection.