
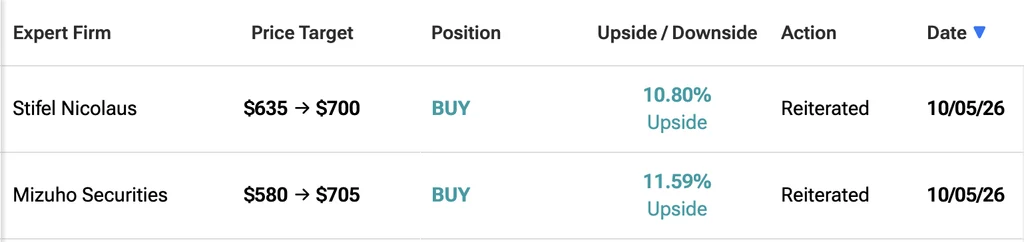
Advanced Micro Devices, Inc. (AMD) maintains its strong standing among Wall Street analysts. Ruben Roy of Stifel Nicolaus has increased AMD’s price target to $700 from $635, representing a 10.80% upside from its present valuation. In parallel, Vijay Rakesh from Mizuho Securities has bumped up expectations from $580 to $705, marking an upside of roughly 11.60%. Let’s examine the catalysts driving these upward revisions on AMD stock.
Why Is Wall Street So Bullish On AMD Stock?
Over the past year, AMD has ranked among the market’s top-performing equities. The artificial intelligence boom has generated one of the most successful periods in the company’s history. As a primary direct competitor to sector leader Nvidia (NVDA), AMD stands out alongside other chipmakers like Intel as the principal challenger to the industry heavyweight. This competitive stance enhances AMD’s appeal to Wall Street, as heightened competition frequently fuels superior innovation and financial gains. Analysts appear confident that AMD will sustain its momentum on the ongoing AI wave.
The upcoming release of AMD’s third-quarter financial results is scheduled for November 3, 2026. Anticipation is high that the November earnings report will demonstrate robust revenue from Helios chip sales. These projections may be prompting analysts to update their outlooks prior to the Q3 report. Additional Wall Street firms could potentially mirror the paths taken by Stifel Nicolaus and Mizuho Securities by elevating their targets for AMD.
Also Read: Ark Invest Buys $81 Million Nvidia Stock, Sells $110 Million AMD
Presently, AMD’s data center division serves as a primary revenue generator. Driven by sustained high demand for AI model training, this trajectory is expected to persist in the years ahead. Data centers are projected to remain the leading revenue source for AMD in its upcoming financial disclosure. This expansion in the data center sector serves as another key factor behind the persistent bullish sentiment from Wall Street analysts.